Financial Planning

Making the case for the reverse mortgage as a retirement planning option | Financial Post

Financial Planning, Retirement

I may be in the minority, but I think that considering a reverse mortgage can, in certain instances, be a viable financial planning alternative scenario. -Jeff

It’s a problem — home-owning seniors retiring with reduced income but healthy levels of consumer and mortgage debt — that seems to contain its own solution.The solution: consider the house as an asset like the others and use it as a way of managing your financial affairs, a move that could make for a more carefree retirement.

Read the entire article: Making the case for the reverse mortgage as a retirement planning option | Financial Post

Making the case for the reverse mortgage as a retirement planning option | Financial Post Read Post »

How Much Income Will You Need For Retirement? | KOB.com

Financial Planning, Retirement

Good article and something that reiterates the point that ‘rules of thumb’ are just not appropriate for everyone. -Jeff

The 80% rule is one of the classic rules of thumb for retirement advice. Financial planners often advise that in order to maintain your current lifestyle in retirement, you should aim to replace 80% of your working income from your retirement resources such as Social Security, investment dividends, and IRA withdrawals.

From that point, you gauge the total amount of money that you need based on when you plan to retire, in other words, how many years you are likely to need income?

Read the entire article: How Much Income Will You Need For Retirement? | KOB.com

How Much Income Will You Need For Retirement? | KOB.com Read Post »

What Assets Need to Be Listed for Probate? | LegalZoom

Financial Planning

Whether it is necessary to probate property can depend upon how title to the property is held, or whether there is a designated beneficiary.

An estate probate can be time-consuming and expensive, so arranging proper titling and beneficiary designations can be important.

What Is Probate? Probate is a legal process, whereby a court oversees the management of a deceased person’s property (or assets) to as

Read the entire article: What Assets Need to Be Listed for Probate? | LegalZoom

What Assets Need to Be Listed for Probate? | LegalZoom Read Post »

3 Smart Ways to Maximize Your Roth IRA — The Motley Fool

Financial Planning

The Roth IRA is an amazing way to create tax-free retirement savings, and it’s something that, frankly, too few people take advantage of. Since it’s our mission to help people invest better, we asked three of our top retirement planning contributors to discuss smart ways you can maximize your Roth IRA. Depending on your situation, there’s a good chance

Read the entire article: 3 Smart Ways to Maximize Your Roth IRA — The Motley Fool

3 Smart Ways to Maximize Your Roth IRA — The Motley Fool Read Post »

3 mistakes to avoid in your first 3 years of retirement – MarketWatch

Financial Planning, Retirement

When you’ve finally arrived at the stoop of retirement, your next steps are often some of the trickiest. So much time and effort goes into reaching this milestone that what you do next is often ignored. Not intentionally, it just happens.

While the day-to-day of the next stage of your life may be unknown, what not to do is actually quite clear: Don’t invest too conservatively, don’t overspend and don’t neglect your health. Seems like common sense,

Read the entire article: 3 mistakes to avoid in your first 3 years of retirement – MarketWatch

3 mistakes to avoid in your first 3 years of retirement – MarketWatch Read Post »

How to Find Previous 401(k) Accounts — The Motley Fool

Financial Planning, Retirement

There are several ways you can try to locate lost retirement money.

Using an employer-sponsored 401(k) plan can be a great way to save for retirement. The downside of 401(k)s, though, is that they are tied to a specific employer. As a result, when you switch jobs, your 401(k) money won’t automatically switch with you. Rather, in many cases, it will stay in your account. Below, we’ll run through

Read the entire article: How to Find Previous 401(k) Accounts — The Motley Fool

How to Find Previous 401(k) Accounts — The Motley Fool Read Post »

The riskiest stock to own? Your employer’s

The riskiest stock to own? Your employer’s

Financial Planning, Retirement

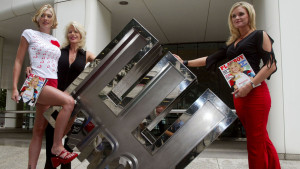
The riskiest stock to own? Your employer’sShortly before Enron collapsed, 62% of employees’ 401(k) assets were invested in Enron. Above, Playboy magazine’s “Women of Enron.” Pension plan consultants, in the wake of a recent Supreme Court case, are telling retirement plan sponsors to reconsider their decision to offer company stock in a 401(k) plan.

You might want to do the very same: Revisit your decision to invest in your company’s stock in your employer-sponsored retirement plan.

Consider: “Defined-contribution plan participants frequently allocate too much of their total retirement portfolio to company stock,” Mark Teborek, a senior consulting analyst with Russell Investments in Chicago, wrote in a recent paper, “Revisiting Company Stock in Defined-contribution Plans.”

In fact, company stock represents on average a whopping 22.5% of defined-contribution assets among plans with more than 5,000 participants, according to the Plan Sponsor Council of America’s 57th Annual Survey, 2014.And that sort of outsize position in company stock might be considered […]

The riskiest stock to own? Your employer’s Read Post »

Opinion: 7 ways to catch up if you’re behind on retirement savings

Opinion: 7 ways to catch up if you’re behind on retirement savings

Financial Planning, Retirement

Opinion: 7 ways to catch up if you’re behind on retirement savingsMost financial advisers agree: The simplest way to ensure you retire comfortably is to start saving early and let the power of compound interest work for you over time.

But what happens if you’re getting a late start on retirement, or financial troubles in middle age ate into your nest egg and now you’re playing catch-up?

The hard reality is that the vast majority of Americans get a late start on retirement planning. Consider a 2011 study from the Schwartz Center for Economic Policy Analysis at The New School, which found a staggering 68% of Americans age 25-64 weren’t even participating in an employer-sponsored retirement plan like a 401(k).

More recently, a 2014 survey from finance website Bankrate.com found more than one-third of Americans don’t have a penny saved for retirement, including more than a quarter of those age 50 to 64.It’s also important to point out that many Americans grossly underestimate […]

Opinion: 7 ways to catch up if you’re behind on retirement savings Read Post »

Reading Your Employee Handbook Can Pay Off In A Big Way Before Retirement

Reading Your Employee Handbook Can Pay Off In A Big Way Before Retirement

Financial Planning, Retirement

Reading Your Employee Handbook Can Pay Off In A Big Way Before RetirementThere are a myriad of things that people must consider before they retire. They contemplate whether they will have enough money or not; if they’ll out live those fund; and whether they have their savings allocated correctly to name a few.

But many people don’t think about flipping through their employee handbook before retirement and as a result may be leaving unclaimed time and money on the table.

I was recently talking to a family member at an event and learned he was retiring. After congratulating him, I asked when the big day was and what led to him making the decision.

He was very specific, including both a date and time.“January 31, at 4pm” he said.“Okay, you’ve really got the date and time nailed down don’t you,” I replied… adding, “Any significance to the 4pm?”He laughed, “Yes I was going to retire at the end of the year but after I […]

Reading Your Employee Handbook Can Pay Off In A Big Way Before Retirement Read Post »

Why Inflation Is Lower Than You Think

Financial Planning, Markets

at-painter1Financial pundits routinely claim that inflation is much higher than the reported statistics. We hear, for example, that food prices have risen much faster than the roughly 1.5% increase in the consumer price index (CPI) over the past several years. Viewed over the longer term, however, inflation is far lower than reflected in the published data.

The reason for this anomaly is that the CPI doesn’t reflect the rapid advances in technology and the new products and services that have benefited everyone.

The implications are profound. For example, real GDP growth is greater than has been reported, and some claims of income inequality are misleading.

This theme was the focus of two recent presentations I attended. On October 18, the economist Woody Brock hosted a private gathering of investment professionals from Australia and New Zealand, organized by the Portfolio Construction Forum , at his home in Gloucester, Massachusetts. On October 22, Rick […]

Why Inflation Is Lower Than You Think Read Post »

Andrea Coombes’ Ways and Means: Your grandchildren will save more for retirement than you

Financial Planning, Retirement

High-Frequency Monitoring: A Short-Sighted Behavior | DealbreakerYoung adults in the U.S. may be getting the message that saving for retirement is on their shoulders — they’re starting to put aside money for retirement years earlier than previous generations. That’s the good news. But when it comes to retirement saving in the U.S., there’s still plenty to worry about, too.

On the good-news front, Generation Y (currently ages 18 to 34) started saving for retirement at age 23, on average, according to a new survey of 1,000 U.S. investors, conducted by CoreData Research for Natixis Global Asset Management.

That’s six years earlier than Gen X (currently ages 35 to 50), who started saving at age 29 on average, and 10 years earlier than the boomer generation (currently ages 51 to 69), who started saving at age 33, according to the survey.

Where will technology be 30 years from now?

(2:09)

The CEOs of Google Ventures and XPRIZE share their predictions for the state of technology 30 years from now.

“That is a significant difference,” said Ed Farrington, executive vice president of retirement at Natixis Global Asset Management. “Time is one of the great allies when it comes to an investment plan. If you start earlier, you have to save a whole lot less and you wind up with a whole lot more — that’s the power of compounding.”

Their smarter savings strategy may be a result of Gen Y, also known as millennials, growing up at a time when the traditional pension was already all but dead, Farrington said. “They perhaps never heard of the promises of a defined-benefit plan or pension,” he said. “They’ve grown up in a world where … they have to put money away for themselves. This is not foreign to them.”

But savers aren’t confident, don’t know how much they need

That said, there is still plenty of uncertainty among retirement savers of all ages. Only 50% of the survey respondents said they’re confident in their investing knowledge and abilities — and their fears appear well-founded. When asked how much money they could safely withdraw each year from a $1 million portfolio that needed to last for 30 years, 60% said 8% or more was a safe withdrawal rate. The safe withdrawal rate rule of thumb is closer to 4%. Read Is the 4% withdrawal rate right for you?.

Meanwhile, 47% of the survey respondents said they’re not sure how much money they need to save for retirement, and 54% of the survey respondents said they don’t believe their savings will provide enough retirement income. Read How much should you save for retirement?

When asked to pin down how much they need to save for retirement, Gen Yers said they need to save about $769,000, on average, and Gen Xers said $741,000. Boomers said they would need $946,000. Read Why you might be saving too much for retirement.

Getting savers on track

The survey also found that employers hold at least one key to improving the state of retirement savings in the U.S.: the power of the match.

Fully 74% of survey respondents cited their company’s 401(k) (or other defined-contribution plan) match as the reason for participating in their company-sponsored retirement plans.

And 50% of those have access to a workplace plan but don’t participate in it cited the lack of a match or said the match was too small, according to the survey.

“The plan sponsor has to make the plan as robust as possible, and then it’s up to the individual to participate, to understand it and to maximize it,” Farrington said, “so that when they get to that point in time [i.e., retirement] they’re prepared.”
Source: Andrea Coombes’ Ways and Means: Your grandchildren will save more for retirement than you

Andrea Coombes’ Ways and Means: Your grandchildren will save more for retirement than you Read Post »

How Thinking About Retirement Shapes Your Life

Financial Planning, Retirement

MW-DQ339_retire_20150717140558_ZH1Many people dream about what they would do all day if they didn’t have to go to work. The key is to dwell on retirement in such a way that it starts to shape your finances. Here’s how my retirement goals have shaped my saving and spending patterns.
I want to be financially secure in retirement, so every dollar I save is the best dollar I will ever spend. I highly value freedom. Saving enough to retire will mean I’m no longer working because I need the cash to survive. I envision a future where I can choose to work only when the endeavor excites me. Whenever I find ways to reduce my spending, I’m really just diverting that money toward a future use.

I want to retire sooner, so I make an effort to increase my income. Working hard throughout your career is a given. But don’t forget about other ways to bump up y…

Read the entire article: How Thinking About Retirement Shapes Your Life

How Thinking About Retirement Shapes Your Life Read Post »

Scroll to Top